

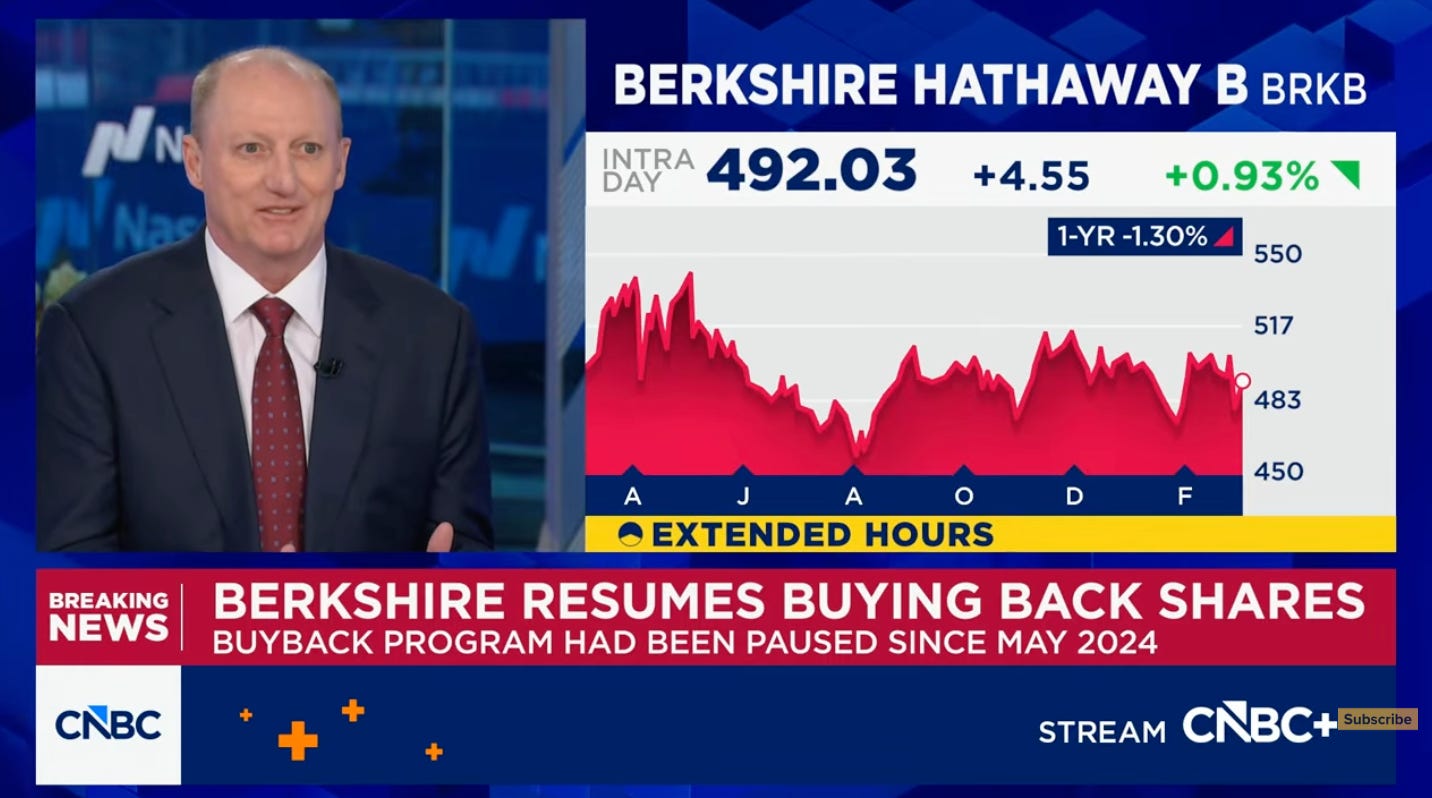
“There’s nothing better than Berkshire. And it’s what I do every day. I wake up, you know, thinking about Berkshire. I go to sleep thinking about Berkshire.” – Greg Abel
Abel jumped onto the set of CNBC last Thursday and discussed a variety of things. Especially topical was Berkshire’s decision to resume share repurchases, and that Abel is using his entire $25 million salary ($15.3 million after tax) to buy shares of BRK on the open market.
This alignment is also not a one-year stint. Abel has committed to allocating 100% of his after-tax salary to shares of BRK annually until he steps down. Abel said this idea was his, and when he approached Buffett with it, he said, “No one else in corporate America does this,” and “This is so Berkshire.”
You can watch the full interview here. It starts at 13:45, and at 16:21, CNBC’s Joe Kernen asked what Berkshire looks at when deciding if a share buyback makes sense.
“Is it a gut feeling more than, are there numbers where you say this hit, you know, 80% of book, this part of Berkshire or something like…”
To which Abel responded, “It’s really just looking at the economic opportunities that exist within Berkshire, and we are comfortable that the value proposition is very strong and we’re doing it on behalf of obviously our shareholders and owners. We have to view this as value that we’re creating value for our shareholders long term.”
Berkshire A shares, of which there are 950 holders on record, closed around $784,000 yesterday. To try to gauge how much value Berkshire is getting, a simple but effective calculation can be made.
Three years’ average net operating earnings per share, excluding gains from marketable securities, plus per share investments. Below are Berkshire’s segmented net earnings from their 2025 annual report.
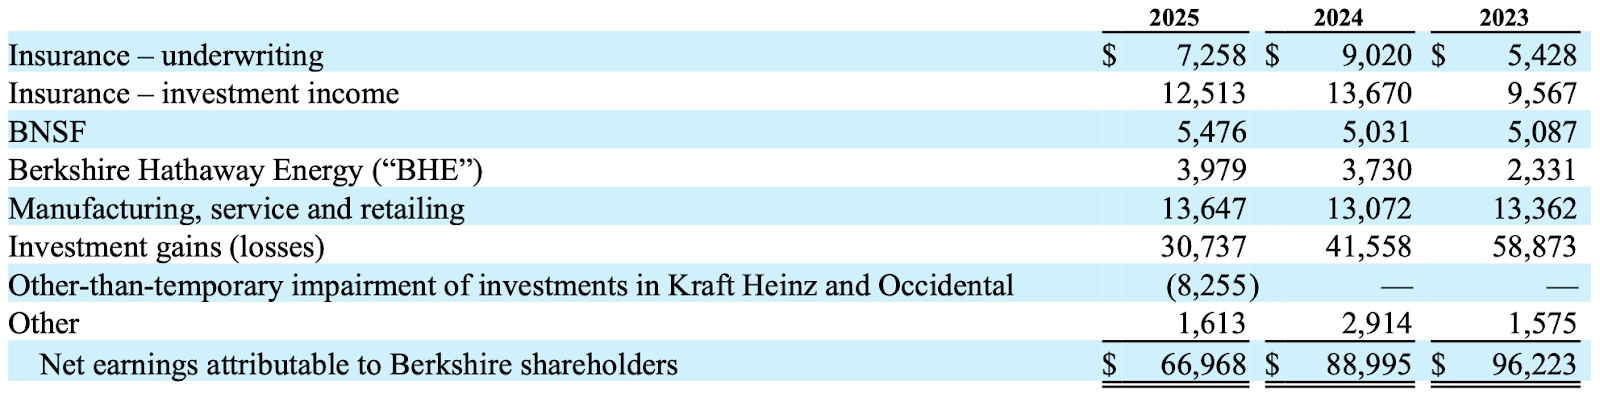
Three years’ average net operating earnings come out to $40.3 billion. On 1.44 million class A shares outstanding, that is $28,020. Capitalizing that at 15x equals $420,310.
Add the investment portfolio of $370 billion of cash and cash equivalents, $17.8 billion of fixed maturity securities, $297.8 billion of equity securities, and $20 billion of equity method investments, all of which totals $706 billion and on a per share basis is $475,800.
Per share net operations of $420,310 plus per share cash and investments of $475,800 equals $896,110. In effect, BRK trades at a 17% discount to its intrinsic value and the prospective investor can now expect to receive at least the full economic return of Berkshire’s underlying business.
Net operating earnings will probably compound at 6% annually as they did in the prior decade, and the investment portfolio should at least provide a similar return. Thus, BRK has the wind to its back, and shareholders will be happy with their position come 2036.
In contrast, it’s probable that the dollars currently being invested in S&P 500 index funds will not experience the joys of compound interest over the next decade.
The index’s P/E ratio of 30 could very well revert to its mean of 16, which completely offsets a doubling of earnings power. Flat to negative returns for the index over this timeframe would result in an approximately 80% outperformance for BRK.
This scenario also implies a possibility of Berkshire taking the top spot as the world’s most valuable company. Ten stocks currently rank ahead of BRK in terms of market cap globally: Nvidia ($4.3T), Apple ($3.8T), Google ($3.6T), Microsoft ($3.1T), Amazon ($2.3T), Taiwan Semiconductor ($1.8T), Saudi Aramco ($1.7T) Meta ($1.6T), Broadcom ($1.6T), and Tesla ($1.5T).
The air will eventually burst out of big tech, Saudi supply chain issues could endure, and China might take Taiwan in the not-too-distant future. Berkshire leapfrogging this group of companies in a rather short period of time is not totally unrealistic.